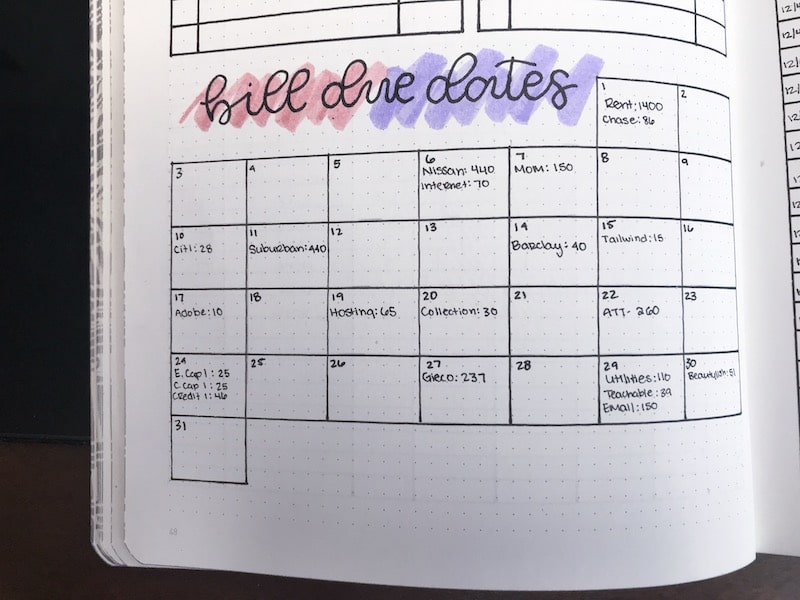
First things first: blowing your budget does not mean you are bad with money. It means you are human. I used to be a professional at turning “just a quick Target run” into a full-blown financial event. The difference between staying stuck and getting back on track is not willpower. It is having a simple recovery plan you can run the minute things go sideways.
Below are seven practical strategies I have used to stabilize cash flow, cover bills, and get your budget breathing again without spiraling into shame.
1) Do a 15-minute money triage
When you realize you overspent, your brain wants to either ignore it or punish you. Neither pays the electric bill. Instead, do a quick triage like you would after a flat tire.
Your 15-minute checklist
- Check your current balances: bank account(s) and credit card balances. If you note “available credit,” do it for awareness so you do not accidentally max out a card or trigger fees, not as permission to spend.
- List the next 7 days of essentials: housing, utilities, insurance, minimum debt payments, childcare, gas, groceries, prescriptions, and any critical medical costs.
- Write down what is due first: dates matter more than categories right now.
- Confirm what income is actually coming in: next paycheck, side gig, reimbursements you can count on.
If you are a zero-based budgeter like me, meaning you assign every dollar a job on paper, this is where you bring reality back into the plan and adjust from here.
2) Freeze spending for 48 hours
Not forever. Just long enough to stop the bleeding.
For the next 48 hours, only buy true essentials (gas to get to work, medication, barebones groceries). That pause creates space for you to make calm decisions instead of emotional ones.
Make it easier on yourself
- Unsubscribe from retail emails and deal alerts for the week.
- Remove saved cards from shopping apps.
- Move fun money categories to cash only until payday.
- Tell one person you trust, “I’m doing a 48-hour spending reset.” Accountability helps.
This is you taking the wheel back.
3) Cover essentials first
If your budget got blown by an unexpected expense, the fastest way to reduce panic is to prioritize the stuff that keeps you safe, housed, and able to earn income. A simple starting point is:
- Housing: rent or mortgage
- Utilities: keep the lights on and the phone working
- Food: simple groceries, not perfection
- Transportation: gas, basic transit, or the minimum to keep the car running
Quick caveat: your “essential” list might look a little different. If you have critical meds, health insurance you cannot let lapse, or a payment that prevents repossession, put that in the essentials bucket too.
Then look at everything else and ask, “Can this be delayed, reduced, or negotiated?”
Quick negotiation targets
- Due dates: ask for a one-time extension. It can be a quick call, and it is worth trying.
- Minimum payments: confirm the true minimum required to stay current.
- Subscriptions: pause or cancel anything nonessential immediately.
- Insurance: if money is tight, ask about changing payment dates or switching payment frequency if it truly helps.
Whenever possible, ask for terms in writing (email confirmation counts) so you are not relying on memory later. And remember that late fees or interest can still apply even when a company is willing to work with you.
4) Make a patch budget
After overspending, many people try to create the world’s strictest budget as punishment. That usually backfires by Friday.
Instead, make a patch budget for the rest of the month. The goal is stability, not budget gymnastics.
Build a patch budget in 10 minutes
- Start with what is left: current cash plus any income arriving before month-end.
- Fund essentials first: your essentials list plus minimum debt payments.
- Create two small relief categories: one for “life happens” ($20 to $50 if possible) and one for “sanity spending” (even $10).
- Everything else becomes a temporary pause: extra debt, sinking funds, nonessential categories. You can restart them next month.
A patch budget gives you permission to be realistic, which is how you actually recover quickly.
5) Find $100 to $300 fast
When I was digging out of debt, I learned that quick cash flow fixes usually come from reducing financial friction, not doing anything heroic.
Do one fast pass through these areas and grab what is easiest first:
- Food: do a pantry week, shift to store brands, plan three cheap dinners you can repeat.
- Transportation: combine errands, pause toll routes if you can, carpool one day a week.
- Subscriptions: cancel or pause immediately. Do not “wait until next cycle.”
- Returns: return unopened items or impulse buys that still have tags.
- One-time sales: sell one item in 24 hours (a small appliance, shoes, a baby item, a gaming accessory).
- Bill check: call your internet provider and ask if there is a current promo or retention rate. Sometimes it works, and it can lower your bill fast.
Even $100 found quickly can be the difference between staying current and sliding into overdrafts or credit card reliance.
6) Do a one-category swap
If you went over in one category (say: dining out, kids activities, or a surprise car repair), you do not have to suffer across the entire budget. You just need a clean trade.
How it works
- Name the overage: “I am $180 over in dining out.”
- Pick one or two categories to reduce: “I will cut groceries by $60 with pantry meals and fun money by $120.”
- Make it visible: adjust your budget app or write the new numbers down.
This keeps you from doing the classic move of whispering “I’ll just be good next month” while nothing actually changes.
7) Do a quick postmortem
This is the step that turns a budget blowout into a learning moment instead of a repeat situation.
Ask yourself three gentle questions:
- What was the trigger? Stress? Celebration? Convenience? A sale? Feeling deprived?
- What was missing from my plan? A sinking fund (a small savings bucket for predictable not-monthly costs), a realistic dining-out amount, a buffer?
- What is one guardrail I can add? Something small that prevents the same thing next time.
Simple guardrails that work
- Create a “stuff I forgot to budget for” line: $25 to $100 each month.
- Make weekends a cash zone: pull your weekend spending in cash on Friday.
- Set a 24-hour rule for non-essentials over $30: add it to a list, buy tomorrow if you still want it.
- Start a sinking fund: car repairs, gifts, travel, back-to-school. Even $10 per paycheck helps.
- Turn on alerts: set low-balance alerts at your bank and spending alerts on your card so you catch drift early.
Real talk: The goal is not to never overspend again. The goal is to build a budget that can take a hit and recover without wrecking your month.
If you are short on bills
If your overspending means you cannot cover a bill, take action quickly. Earlier is usually easier than later.
- Call the company today: ask about a payment plan, a due date change, or a one-time extension.
- Watch autopays: pause or reschedule automatic payments that could trigger overdrafts, and confirm any changes went through.
- Prioritize keeping housing and utilities stable: protect your ability to work and live safely.
- Avoid payday loans if you can: they solve a short problem by creating a bigger one.
- If you are already stuck in payday loan debt: look for a nonprofit credit counselor who can help you map a payoff plan and negotiate where possible.
- Check community resources if needed: local utility assistance, food pantries, or mutual aid can help you stabilize while you rebuild.
No shame. Just steps.
Your next 7 days
- Day 1: 15-minute money triage + 48-hour reset
- Day 2: patch budget for the rest of the month
- Day 3: cancel subscriptions + schedule any needed calls
- Day 4: pantry meal plan + grocery list for essentials only
- Day 5: one-category swap to cover the overspend
- Day 6: return items or sell one thing
- Day 7: postmortem + add one guardrail
That is it. You do not need a brand new personality. You just need a repeatable system.